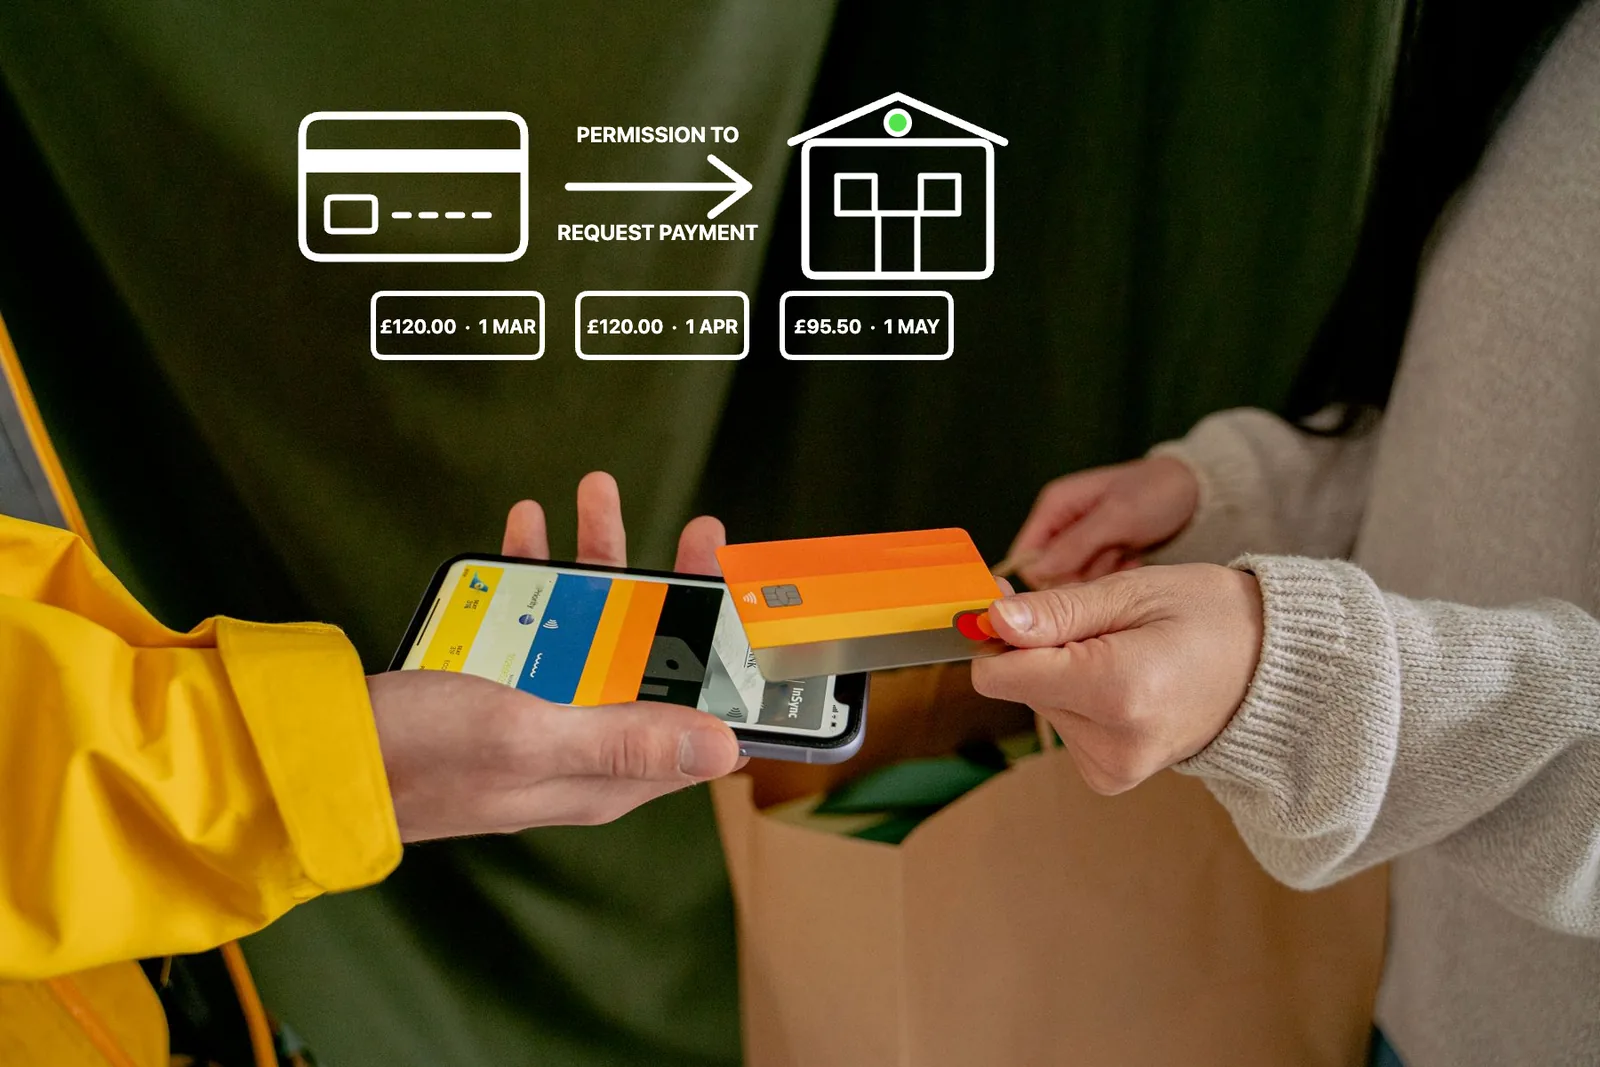
A continuous payment authority lets a business request payments from your debit or credit card. It is not the same as a Direct Debit or standing order.
You can cancel it through the business or through the card issuer. Cancelling the authority does not cancel the loan, the contract or the money owed.
- £120.001 Mar
- £120.001 Apr
- £95.501 May
One authority can permit recurring payments, and the amount can vary if the terms allow it. Example amounts and dates only.
What is a continuous payment authority?
A continuous payment authority, usually shortened to CPA, gives a business permission to request payments from your debit or credit card.
It is also called a recurring card payment, recurring transaction or future card payment.
You may create a CPA when you give a business your long card number, expiry date and other card details and agree that it can take future payments. CPAs are used for services such as insurance, gym memberships and subscriptions. Some lenders also use them to collect loan repayments.
A CPA is different from making one card payment. The permission allows the business to request further payments under the terms you accepted.
The business cannot take any amount whenever it chooses. Your consent should be clear, specific and informed. You should be given enough information to understand how the authority will be used.
How does a CPA work for a loan?
When a continuous payment authority loan is set up, the lender sends a payment request to the company that issued your card. The card issuer then attempts to take the payment from the account connected to the card.
The credit agreement should explain:
That a continuous payment authority will be used.
How it will work.
The amounts or basis on which payments may be taken.
When or how often requests may be made.
How you can cancel the authority.
Whether another repayment method is available.
What may happen if a payment fails.
The lender must use the CPA in line with the agreement and the explanation given to you. The FCA sets out the information a lender must give before the agreement is made. A lender that wants to change its terms must normally explain the proposed change and obtain your consent.
If you are comparing the cost of a loan, the payment method is separate from the price. The APR and total amount repayable tell you what the loan costs; the CPA only controls how the repayments are collected.
CPA, Direct Debit and standing order compared
The payment method controls how money is collected. It does not decide whether the underlying bill, loan or contract remains payable. MoneyHelper explains the three methods in its guide to Direct Debits, standing orders and recurring card payments, and the products they usually pay for are compared in Loans, Overdrafts and Credit Cards Compared.
What type of payment is this?
Answer yes to the question that matches how the payment was set up. One result is shown at a time.
- 01Did you give the business your long debit or credit card number?
- 02Did you complete a mandate using your sort code and bank account number?
- 03Did you create a fixed payment yourself through online or mobile banking?
This tool helps identify common payment methods. Your bank or card issuer can confirm how a specific payment has been set up. No answers are saved or transmitted.
How to recognise a CPA
A recurring card payment may appear in the card payment section of your bank statement rather than the Direct Debit section.
The name on the statement may be the business name, a trading name or the name of its payment processor. If you do not recognise it, do not assume immediately that it is fraud. Ask your card issuer for more information about the merchant and payment type.
A CPA is more likely if:
You supplied card details rather than bank account details.
The payment appears as a card transaction.
It does not appear in your list of Direct Debits.
The amount or payment date has changed under the agreed terms.
Your bank describes it as a recurring card payment.
Can you cancel a continuous payment authority?
Yes. You can cancel a continuous payment authority by contacting either:
The business taking the payments.
The bank or card provider that issued your card.
Your card issuer cannot insist that you contact the business first.
Where possible, tell the lender or business as well as the card issuer. This gives the business an opportunity to update its records and arrange another payment method if money remains due.
To stop the next payment, the FCA says the cancellation request must be made by the end of the business day before that payment is due. Acting earlier gives more time for the instruction to be processed.
Keep evidence of the cancellation. Record:
The date and time.
How the request was made.
The name of the person you spoke to.
Any reference number.
Copies of emails or messages.
Confirmation from the card issuer.
Cancellation scripts
Tell the lender or business
“I am withdrawing my consent for you to take further payments using the continuous payment authority connected to my card. Please cancel the authority and confirm this in writing. Please also tell me whether any money remains due and which alternative payment methods are available.”
Tell the card issuer
“I withdraw my consent for further recurring card payments to [business name] from my card ending [last four digits]. Please cancel the continuous payment authority and confirm when the cancellation takes effect.”
Replace the bracketed details when you send the second message. Do not send your full card number.
What does cancelling a CPA actually stop?
What if a payment is taken after cancellation?
A payment taken after cancellation, where the CPA has been properly cancelled, is treated as unauthorised.
Contact the card issuer and provide evidence showing when the cancellation request was made. Ask for the payment and any related charges to be refunded.
The FCA states that the card issuer must refund further payments taken after cancellation immediately.
If the card issuer refuses or does not resolve the problem, make a formal complaint. Keep the cancellation confirmation, statements and complaint reference.
If you remain unhappy after the card issuer’s final response, or it has not responded within the applicable complaint period, you may be able to refer the complaint to the Financial Ombudsman Service.
A refund is not automatic in every dispute. Where the cancellation was requested too late, or there is disagreement about whether valid consent was withdrawn, the card issuer may reach a different view.
What if you never agreed to the CPA?
A business can only take recurring card payments with your consent. The consent should be clear, specific and informed.
If you did not know you were agreeing to recurring payments, contact your card issuer. Explain why you believe the payments were not authorised and ask it to stop further transactions.
Also contact the business if it is safe and practical to do so. Ask for:
A copy of the authority.
The date on which consent was obtained.
The terms you were shown.
The payment schedule you allegedly accepted.
If you believe the payment is fraudulent, report it to the card issuer immediately and follow its fraud process. It is also worth checking your credit file for accounts or searches you do not recognise.
CPA rules for high cost short term loans
A rule that does not apply to every CPA
Special FCA rules restrict the use of CPAs for high cost short term credit. These payday loan CPA rules are set out in FCA CONC 7.6.
For this type of credit, a lender is generally limited to two unsuccessful CPA requests for the same amount due. Where the loan is repaid in instalments, the rules apply to attempts to collect an individual instalment and affect whether later instalments can be requested.
A high cost short term lender must not normally use a CPA to collect less than the full amount due. A reduced amount may be collected under a properly agreed repayment plan or in other circumstances allowed by the FCA rules, including where the customer has given the required consent.
The two attempt restriction applies to high cost short term credit. It is not a general rule for every lender or every CPA.
What must a lender consider if you are struggling?
A lender must exercise CPA rights in a reasonable, proportionate and not excessive way. It must also consider financial difficulty.
The FCA rules state that a lender must not exercise its CPA rights when it has the required evidence, or otherwise becomes aware, that the customer is in financial difficulty and cannot afford to repay the debt.
A lender should not repeatedly try different dates or amounts in a way that makes the customer’s position worse.
If a payment has failed, speak to the lender. Explain:
Why the money was unavailable.
Whether the problem is temporary or continuing.
What you can afford after essential living costs.
When your circumstances may change.
How you would prefer to make future payments.
Do not promise more than you can afford.
Should you cancel a loan CPA if money is tight?
Cancelling a CPA may stop the lender taking a card payment automatically, but it does not solve the repayment problem.
Contact the lender before the payment date where possible. Ask what support may be available and whether another payment arrangement can be agreed. What Happens if You Miss a Repayment? explains what to expect if a payment is not made.
If taking the payment would leave you unable to afford essentials such as food, housing or energy, consider speaking to a free debt adviser. MoneyHelper’s bill prioritiser can help you identify priority bills and find free debt advice.
Do not take another high cost loan simply to make the payment. This can create another repayment and make the situation harder.
What if your card is replaced?
Do not assume replacing, freezing or cancelling the physical card will cancel every recurring payment authority.
Card payment arrangements can be handled differently by card issuers and payment networks. If you want to stop a CPA, give a clear cancellation instruction to the business or card issuer.
Ask for confirmation that the recurring authority itself has been stopped.
How to complain
If the problem concerns the lender’s use of the CPA, complain to the lender.
If the problem concerns the card issuer failing to cancel the authority or refunding a payment taken after cancellation, complain to the card issuer.
Your complaint should include:
The business name.
The date you cancelled.
How you cancelled.
The date and amount of the disputed payment.
Copies of confirmations and statements.
What you want the business to do.
If the complaint remains unresolved, the Financial Ombudsman Service may be able to review it.
Frequently asked questions
No. A CPA uses debit or credit card details. A Direct Debit uses bank account details and operates through the Direct Debit system.
Your card issuer should act on your cancellation instruction and cannot insist that you contact the business first. Make the request by the end of the business day before the next payment is due.
No. It stops the payment method, not the credit agreement. Any amount owed remains payable and missed payment consequences may still apply.
The authority may allow amounts to vary, but the lender must act within the agreement and the explanation provided. Changes to the terms of the authority normally require an explanation and consent.
General CPA use must be reasonable and proportionate. High cost short term lenders are subject to specific restrictions that normally limit unsuccessful attempts to two for the relevant amount or instalment.
Special rules restrict high cost short term lenders from collecting part payments through a CPA unless the collection is permitted under an agreed arrangement or another applicable exception. Other CPA arrangements depend on the authority and agreement.
The repayment may become overdue. Interest, charges and credit reporting may apply depending on the agreement. Contact the lender rather than waiting for another collection attempt.
A payment taken after an effective cancellation is considered unauthorised. Contact the card issuer, provide evidence of cancellation and request a refund of the payment and related charges.
Keep control of the payment
A CPA is permission to request payments from your card. You can cancel that permission through the business or card issuer. Cancellation does not remove the debt, so contact the lender and arrange another way to deal with any money owed.
LoansForBadCreditUK.co.uk is a credit broker, not a lender. We do not collect repayments or control the continuous payment authority used by a lender. Contact the lender named in your credit agreement or your card issuer for help with a specific payment.
This guide provides general information and is not personal financial or debt advice.