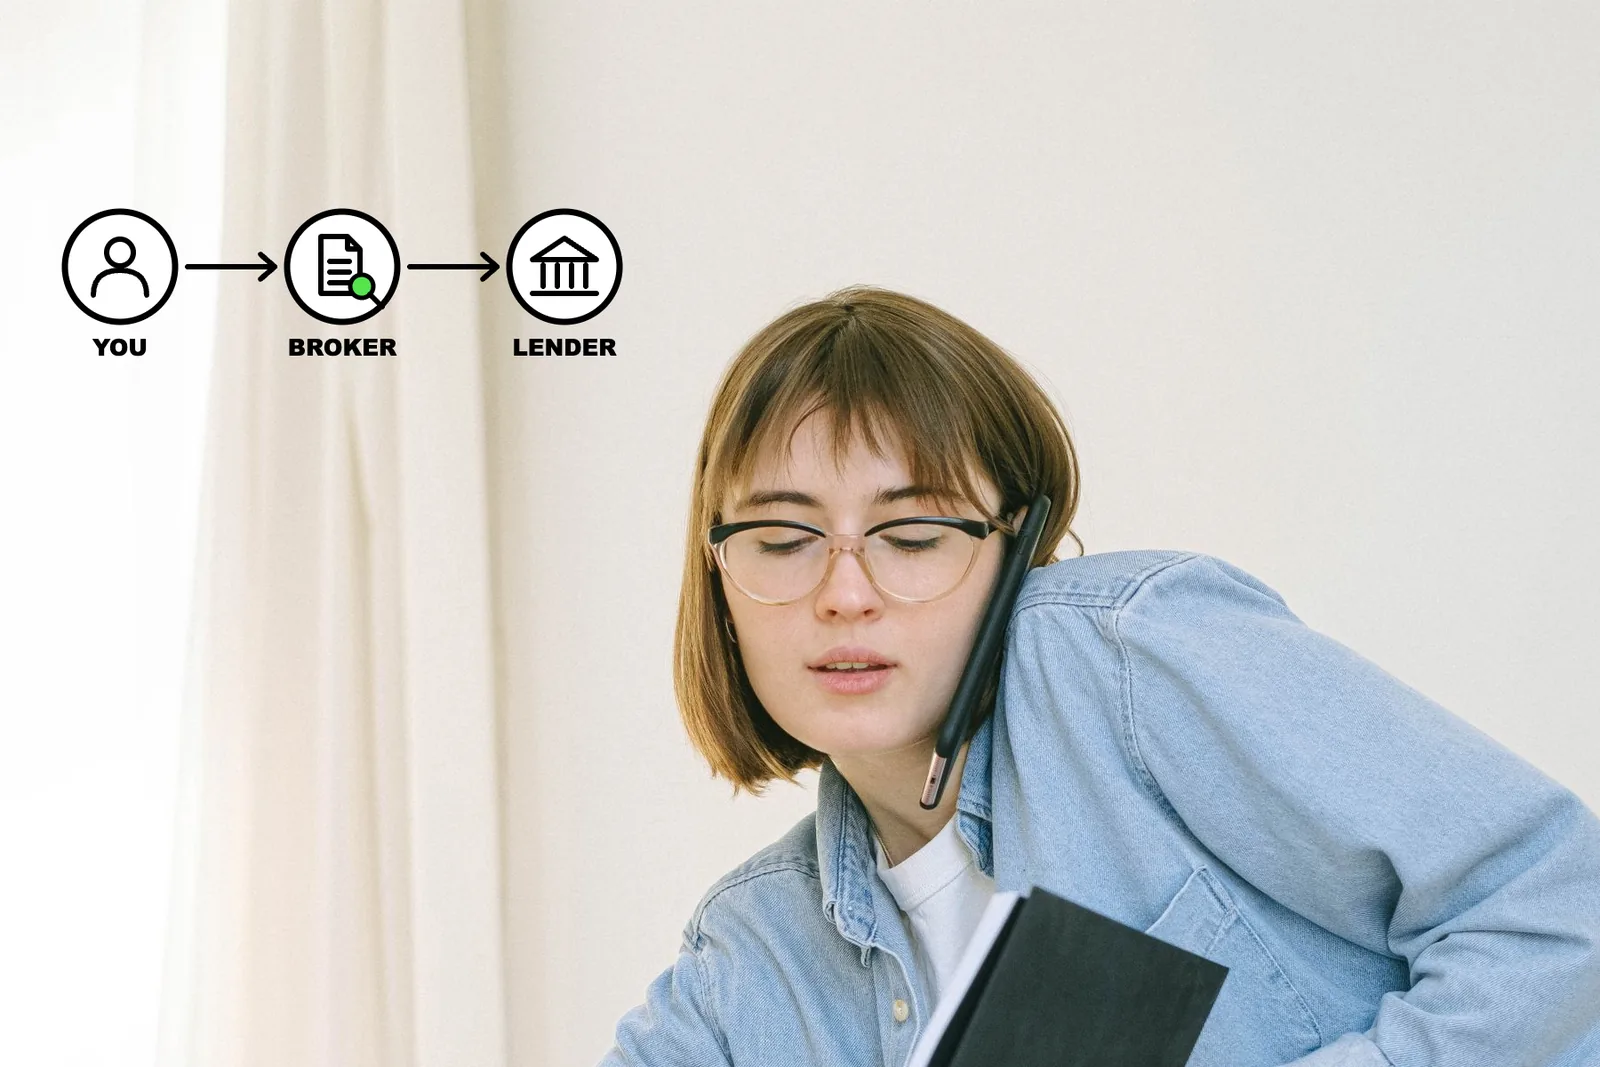
A credit broker helps connect people looking for credit with businesses that may be able to provide it. The broker does not normally lend the money itself.
Loans for Bad Credit UK is a credit broker, not a lender. We provide a matching service using a panel of participating lenders and brokers. If a possible match is found, the lender still decides whether to accept your application, how much it may offer and what rate will apply.
The journey from application to loan
A credit-broking service usually involves several separate stages.
- YouYou provide your details
- BrokerThe broker searches its panel
- BrokerA possible match is identified
- LenderThe lender assesses the application
- LenderThe lender provides the money if approved
Being matched with a lender is not the same as being approved.
1. You provide your details
You complete an application or eligibility form with information such as:
- Your name and address
- Your income
- Your employment status
- Your regular spending
- Your existing credit commitments
- The amount you want to borrow
- Your preferred repayment term
The information should be accurate and complete. Entering a larger income or smaller expenses than you really have does not make a loan genuinely affordable.
2. The broker searches its panel
The broker uses the information provided to look for participating firms whose basic criteria may fit the application.
This can save you from visiting several websites and entering the same information repeatedly.
A panel is not the whole credit market. It only includes the lenders and other brokers with which the credit broker has an arrangement.
The broker may search the panel in a particular order. An application is not necessarily sent to every panel member at the same time.
3. A possible match is identified
If a participating firm appears able to consider the application, the broker may introduce you or securely pass on the relevant information.
Depending on the matching route, that firm could be a direct lender or another credit broker with access to a different panel. The privacy notice should explain who may receive your information and why.
A match is not an approval. It means only that another firm may be willing to consider the application.
4. The lender carries out its assessment
The lender makes the actual credit decision.
It may assess:
- Your credit history
- Your income
- Your essential spending
- Existing debts
- The proposed repayment
- Identity and fraud-prevention information
- Its own lending rules
The lender may ask for more information or complete its own credit search. A full application may leave a hard search on your credit report.
The broker cannot control the lender’s decision or guarantee that an offer will be made.
5. You review the lender’s offer
If approved, the lender provides the proposed amount, repayment term, interest rate, APR and total amount repayable.
Read these figures carefully. The terms may be different from the amount or duration originally requested.
You are not required to accept an offer simply because a broker found it.
If you accept, the credit agreement is between you and the lender. The lender provides the money and collects the repayments.
What a broker can and cannot do
A broker can provide an application route, search its participating panel and introduce you to a firm that may be able to help.
A broker cannot:
- Approve the lender’s application
- Set the final interest rate
- Guarantee the requested amount
- Guarantee when money will arrive
- Change the lender’s agreement
- Make an unsuitable loan affordable
The final decision always belongs to the lender.
Does using a broker affect your credit score?
The answer depends on the type of search completed.
A soft eligibility search should not affect your credit score and is not normally visible to other lenders. It may be used during an early matching stage.
A lender may later complete a hard credit search before making its final decision. Hard searches are visible on your credit report.
Check what type of search will take place before continuing. Being matched through a soft search does not guarantee that the later full application will be accepted.
How does a credit broker make money?
A credit broker may receive commission from a lender or commercial partner when it makes an introduction or when a customer enters into a credit agreement.
This means the customer may not need to pay the broker directly.
Loans for Bad Credit UK does not charge customers for using its matching service. The business may receive commission from a lender or partner. More information is available in the website’s commission disclosure.
Some credit brokers do charge customer fees. Where a fee applies, it should be explained clearly, including the amount, when it is payable and the service being provided.
Be cautious if an unfamiliar business contacts you unexpectedly and demands an upfront payment before releasing a loan. Check the firm on the FCA Register and confirm its contact details independently.
How is your information used?
A broker needs permission to use the details you submit for the purposes explained in its privacy notice.
Before applying, check:
- Which business operates the service
- Whether it is a broker or lender
- Which types of firms may receive your details
- How your information may be used
- Whether marketing permission is optional
- How to withdraw marketing consent
Only submit an application if you understand the role of the broker and how your information may be shared.
Is using a broker better than applying directly?
Neither route is automatically better.
Applying directly may suit someone who has already chosen a particular lender. A broker may be useful when someone wants one service to search a participating panel for possible options.
The broker’s panel will not include every lender in the market, and a match does not guarantee that the available offer will be suitable.
Always compare the APR, monthly repayment, repayment term and total amount repayable before accepting credit.
Frequently asked questions
No. A broker arranges or introduces possible credit. The lender assesses the application, provides the money and enters into the credit agreement.
No. A broker may identify a possible match, but only the lender can approve an application.
Not necessarily. The broker searches or refers the application within its participating panel. The process and possible recipients should be explained in the privacy notice.
No. Review the rate, repayments, term and total cost before deciding. You can decline an offer.
Once a loan has been accepted, repayment questions should normally be directed to the lender named in the credit agreement.
The important distinction
A credit broker opens a route to participating firms. It does not make the lending decision.
The broker searches for a potential match. The lender decides whether to offer credit, sets the terms and provides the funds.
Credit is subject to status and affordability checks. Neither a broker nor a lender can guarantee acceptance.